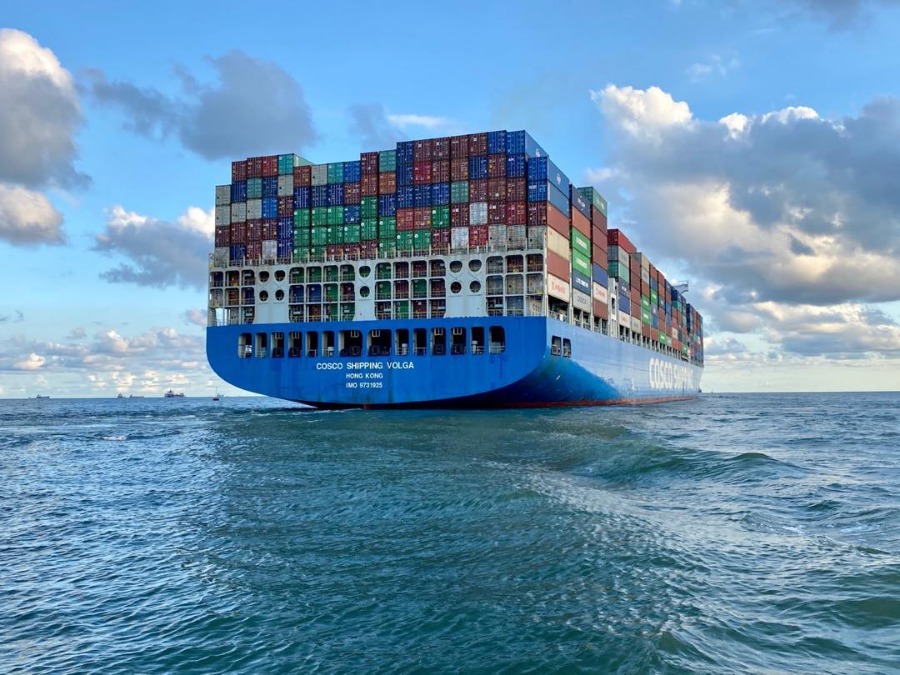
International maritime container transport is becoming increasingly concentrated in the hands of a small group of companies. Data released by specialized consultancy Alphaliner reveals that the world's four largest shipping companies already control 58.7% of global container fleet capacity, solidifying a trend that has been intensifying over the past decade.
Leading the ranking is MSC, which surpassed the 7.3 million TEU capacity mark and now holds 21.6% of the global fleet by itself. The Swiss company has significantly widened its lead over second-place Maersk, which is responsible for 13.8% of global capacity.
Completing the group of giants are CMA CGM and COSCO Shipping Lines. Together, the four companies concentrate nearly three-fifths of all global capacity dedicated to regular container transport.
The survey also shows that the world's ten largest shipowners currently account for more than 84% of available global capacity, leaving an increasingly smaller share of the market for medium and small operators.
Consolidation reshapes the sector
The current scenario is the result of a lengthy consolidation process marked by mergers, acquisitions, operational alliances, and billion-dollar investments in large-capacity vessels.
About ten years ago, the four largest shipowners concentrated approximately half of global capacity. Today, that share approaches 60%, evidencing the growing influence of a reduced number of companies over global logistics.

MSC's leadership is one of the main examples of this movement. After surpassing Maersk in operational capacity, the company continued expanding its fleet through the acquisition of used vessels and the incorporation of new ships.
Currently, the gap between MSC and Maersk exceeds 2.6 million TEUs, a volume larger than the combined capacity of various shipowners ranked between eighth and tenth position globally.
Impacts for Brazil
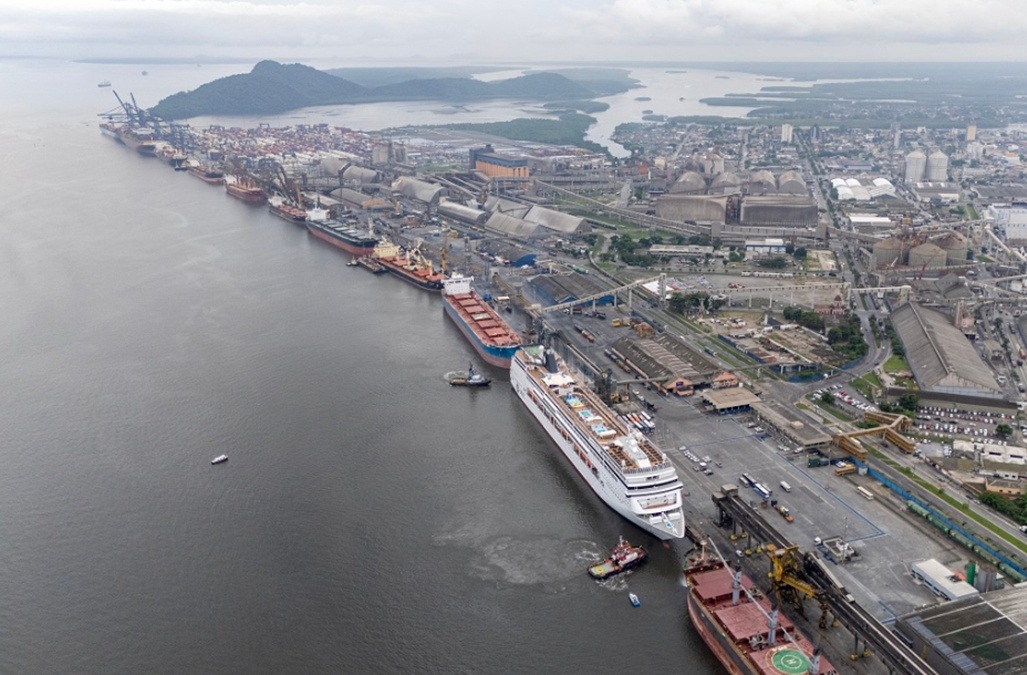
Market concentration has direct effects on Brazilian foreign trade. The leading companies in the ranking operate regularly in national ports, including Santos Port, Paranaguá Port, Itapoá Port, Navegantes Port, Rio Grande Port, Salvador Port, and Pecém Port.
These companies transport a significant portion of Brazilian exports of proteins, cellulose, coffee, cotton, chemical products and manufactured goods, in addition to serving much of Brazil's imports of manufactured goods and productive inputs.
With fewer operators dominating the market, decisions related to the supply of cargo space, frequency of calls, container availability, and commercial strategies now have an even greater impact on exporters and importers.
Asia expands its prominence
The ranking also highlights the strengthening of Asian shipowners. Among the world's ten largest groups, five are headquartered in Asia, including COSCO, Ocean Network Express, Evergreen Marine, HMM, and Yang Ming Marine Transport.
``` ```htmlThe growing presence of these companies tracks the expansion of Asian production chains and the strengthening of trade routes linking Asia to Latin America, a market that has been receiving significant maritime capacity investments in recent years.
More ships, greater competition
Despite growing consolidation, global capacity continues to increase. The worldwide container fleet already exceeds 34 million TEUs and is expected to grow further with the delivery of new mega-container vessels currently under construction.
For experts, the main challenge for the sector will be balancing fleet growth with the evolution of global demand. Should fleet expansion advance at a pace faster than international trade, shipowners could face greater competitive pressure and lower freight rates on certain routes.
Meanwhile, consolidation continues to reshape global logistics. For Brazilian companies that depend on maritime transport, decisions made by an ever-smaller group of shipowners tend to directly influence logistics costs, space availability, and competitiveness in international trade.
```